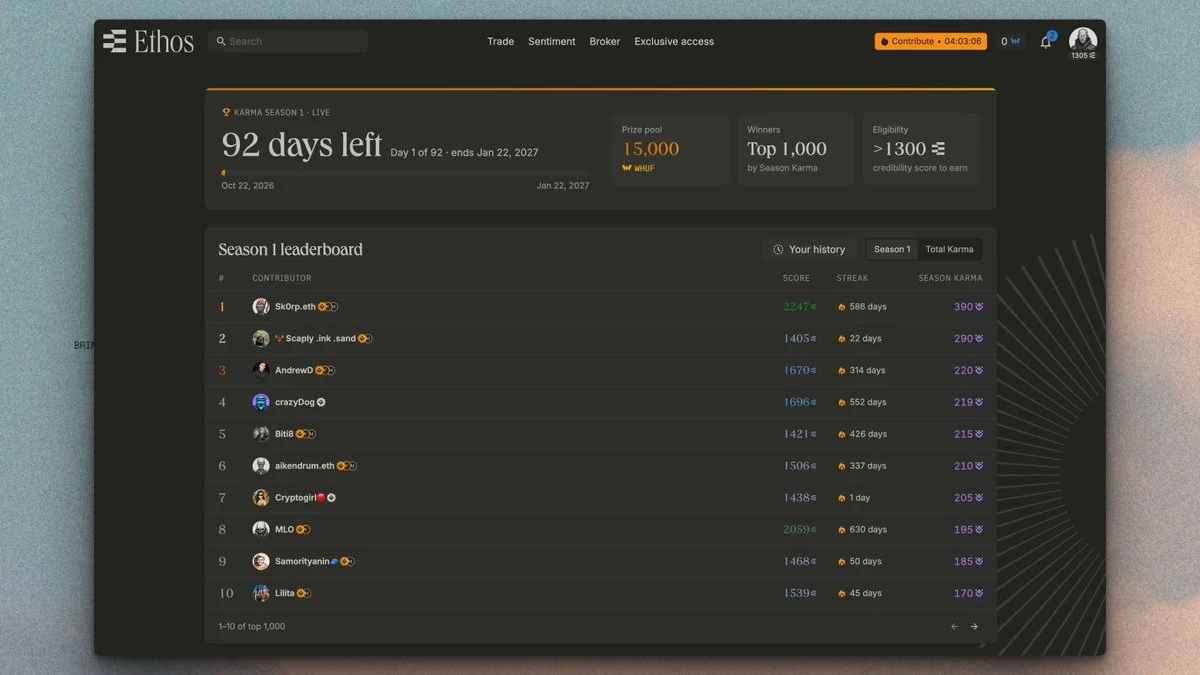
Credifi lets anyone with an Ethos Credibility Score of 1800+ borrow up to $3,000 with no collateral, no KYC and no liquidation. As of October 5, 2026, the team reported zero defaults across its first lending cohort.
That matters because onchain lending has, until now, worked almost entirely one way. We covered the zero-default update when it came out. This piece looks at the loan terms, the reaction to the launch, and how the model compares with DeFi and bank lending.
The problem with onchain credit
DeFi has only ever solved one kind of loan: the overcollateralized kind. To borrow $3,000, you first have to lock up more than $3,000. Real credit runs on trust, and onchain there has been no cheap way to underwrite it.
Credifi’s approach is to read your Ethos Credibility Score and turn it into a credit line.
How a Credifi loan works
- Score: Credifi reads your Ethos Credibility Score. A score of 1800+ qualifies.
- Borrow: you draw up to $3,000 unsecured, with no collateral, no lockup and no KYC.
- Repay: repaying builds your credit. Your reputation is what backs the loan.
The terms at a glance:
- Max unsecured loan: $3,000
- Ethos score to qualify: 1800+
- Liquidation: none
- KYC: none
- Speed: instant
- Model: reputation credit
The reaction to the launch
Credifi announced the integration on August 27, 2026. A day later, Jesse Pollak (jesse.base.eth), founder of Base, quote-posted it with four words:
“onchain native undercollateralized credit”
Figures from X as of October 1, 2026:
- Credifi announcement: 697.2K views, 994 likes and 192 reposts
- Jesse Pollak’s quote post: 272.5K views
Zero defaults in the first cohort
Nearly a month after unsecured credit went live, Credifi reported zero credit defaults across its initial lending cohort. Every loan was unsecured and every borrower was anonymous. The only thing underwriting them was an Ethos Credibility Score.
Some borrowers even posted on X that they would not pay it back. They paid anyway.
mod323, co-founder of Credifi, put it this way on October 5, 2026:
“Everyone told us unsecured lending to anons would never work. One month in, the first cohort has zero defaults. Reputation turned out to be collateral people actually protect.”
Why reputation can stand in for collateral
An Ethos score of 1800+ reflects three things that aren’t cheap to manufacture:
- Real reviews from other people
- ETH that others have staked on you through vouches
- Human Verification
If a borrower defaults, they burn the one asset they can’t quickly rebuild: their onchain reputation. The first cohort bore that out, with zero defaults to date.
How it compares with DeFi and bank loans
- DeFi loan: over 100% collateral required, no KYC, liquidation risk, underwritten by your deposit, instant
- Bank or card: collateral sometimes required, KYC required, no liquidation risk, underwritten by a credit bureau, takes days
- Credifi with Ethos: no collateral, no KYC, no liquidation risk, underwritten by your reputation and onchain history, instant
In short, the borrower puts up their reputation rather than their assets, and repaying is how they keep it.
What other lenders could take from it
The same approach could work for any lending protocol that wants to underwrite trust:
- Unsecured credit lines: set a borrowing limit by credibility score instead of by deposit
- Reduced collateral: offer lower collateral requirements to high-credibility users
- Credit building: let repayment build a borrower’s credit over time
This article is adapted from the Ethos case study.